Egg Weekly(Sep 10)
Egg Weekly: The "Last Stand" of Mid-Autumn Festival?
Contents
1、1. Domestic Egg Market Analysis
1.1 Egg Market Price Analysis
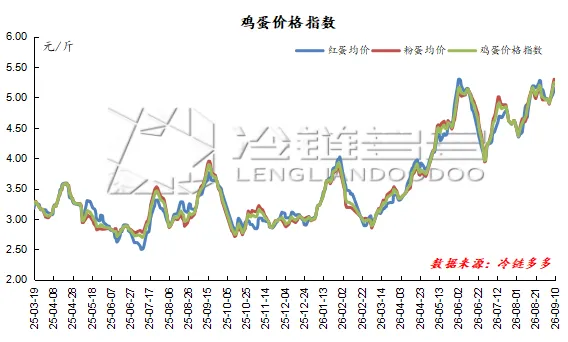
This week, domestic egg prices showed a rebound trend. As of Thursday, the average price of red-shell eggs was 5.15 yuan/jin, up 0.19 yuan/jin from last week, and the average price of white-shell eggs was 5.29 yuan/jin, up 0.36 yuan/jin from last week. Both red and white egg prices showed varying degrees of rebound, with the price spread widening to 0.14 yuan/jin.
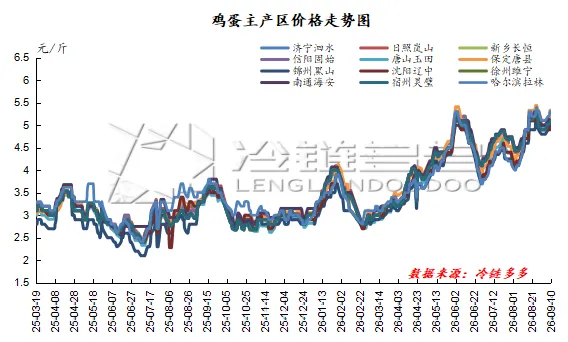
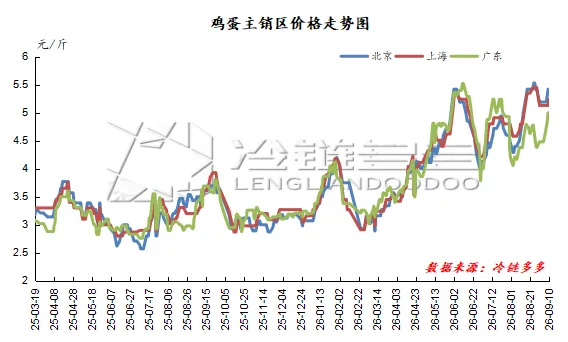
Egg prices showed a slight rebound this week. Mid-Autumn Festival stocking demand continues to be released, providing phase-specific support to the market. However, as egg prices rise, downstream purchasers have become more cautious, buying based on their own sales pace with limited willingness to stock up. Supply rhythm remains steady. The production area market overall ran relatively strong, but the increase was moderate.
Production Area Market: The average price of eggs in main production areas was 5.17 yuan/jin as of Thursday, up 0.22 yuan/jin from last Thursday.
Consumption Area Market: The average price of eggs in main consumption areas was 5.19 yuan/jin as of Thursday, up 0.26 yuan/jin from last Thursday.
1.2 Egg Market Price Trend Charts
1.3 Weekly Domestic Egg Regional Price Comparison
|
Weekly Egg Price Comparison by Region (Unit: yuan/jin) |
|||||
|
Region |
Market |
Sep 10 |
Sep 3 |
Change |
Notes |
|
East China |
Nantong Haian |
5.10 |
5.00 |
0.10 |
Basket delivered price |
|
Dezhou Ningjin |
5.10 |
4.83 |
0.27 |
Basket delivered price |
|
|
Suzhou Lingbi |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Xuzhou Juning |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Rizhao Lanshan |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Jining Sishui |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Central China |
Hubei Xiantao |
5.20 |
4.87 |
0.33 |
Box-included point price |
|
Hubei Xishui |
5.42 |
5.13 |
0.29 |
Box-included point price |
|
|
Xinxiang Changheng |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Xinyang Gushi |
5.10 |
4.90 |
0.20 |
Basket delivered price |
|
|
Northeast |
Harbin Lalin |
5.30 |
5.10 |
0.20 |
Basket delivered price |
|
Changchun Dehui |
5.20 |
5.10 |
0.10 |
Basket delivered price |
|
|
Jinzhou Heishan |
4.90 |
4.80 |
0.10 |
Box delivered price |
|
|
Shenyang Liaozhong |
5.10 |
5.00 |
0.10 |
Basket delivered price |
|
|
North China |
Shijiazhuang Xinji |
4.78 |
4.24 |
0.54 |
Basket delivered price |
|
Baoding Tangxian |
5.33 |
5.11 |
0.22 |
Basket delivered price |
|
|
Cangzhou Cangxian |
5.20 |
5.05 |
0.15 |
Basket delivered price |
|
|
Handan Guantao |
4.82 |
4.49 |
0.33 |
Box three-wheeler transport |
|
|
Hengshui Raoyang |
4.78 |
4.24 |
0.54 |
Box point price |
|
|
Southwest |
Kunming Guandu |
5.56 |
5.44 |
0.12 |
Basket delivered price |
|
Wenjiachang |
5.40 |
5.00 |
0.40 |
Net weight point price |
|
2、2. Laying Hen Inventory and Slaughter Analysis
2.1 Inventory Analysis
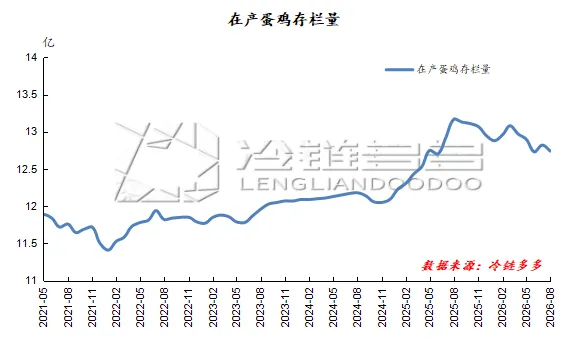
From the inventory structure perspective, current laying hen farming profits are acceptable. Large enterprises restocking is relatively normal, but small and medium-sized farmers restocking willingness is moderate. The restocking volume in April-May was at a relatively high level year-to-date, meaning newly productive hens will face a wave of concentrated supply, and the supply side will see noticeable improvement.
2.2 Slaughter Analysis
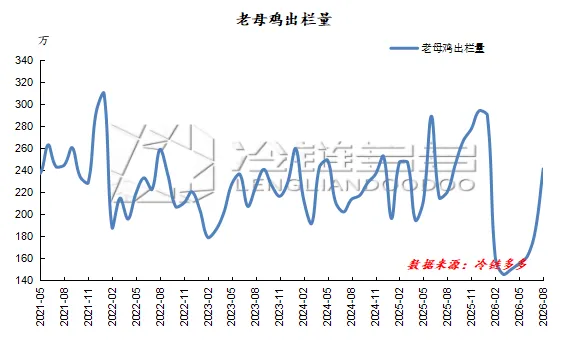
Regarding culling, recent hen slaughter volumes increased month-on-month, but the age at culling continues to be delayed. Farmers expectations for post-Mid-Autumn market conditions are somewhat bearish, and culling willingness has strengthened somewhat, but the overall pace remains at normal levels and has not yet entered an over-culling phase.
3、3. Egg Demand Analysis
The Mid-Autumn Festival effect continues to provide some support to demand. Terminal retail and gift box packaging demand are gradually being released. After the market sales pace accelerated, inventory at production and distribution levels remained at low levels.
4. Egg Market Outlook
From the supply side, newly productive hens in September mainly correspond to the chicks restocked in April-May. The surge in egg prices in May combined with the spring restocking peak season boosted farmers restocking enthusiasm. This batch of chicks has been successively entering production since September, and the number of newly productive hens continues to grow. Regarding culling, recent hen slaughter volumes increased month-on-month, but the age at culling continues to be delayed.
From the demand side, supporting strength tends to weaken. Demand shows clear structural differentiation - the market favors small and medium-sized premium eggs, while large-sized eggs sell relatively moderately. As egg prices rise, downstream purchasers become more cautious, buying based on their own sales pace with limited willingness to stock up. Although food processing enterprises are in the pre-Mid-Autumn
Overall, the Mid-Autumn stocking window is running out. The festival effect still provides phase-specific floor support to egg prices, but underlying market contradictions are gradually emerging. The market for large and small eggs may diverge - large eggs trend weakly while small and medium eggs retain some resilience supported by gift box demand. As post-Festival demand gradually fades, supply side pressure will be fully released, and egg prices face considerable downward risk. The adjustment is expected to be around 0.50 yuan/jin, with main production area averages at 4.70-7.90 yuan/jin.