Egg Weekly: Running High, Rally Moderating(Sep 17)
Egg Weekly: Running High, Rally Moderating
I. Domestic Egg Market Analysis
1.1 Egg Market Price Analysis
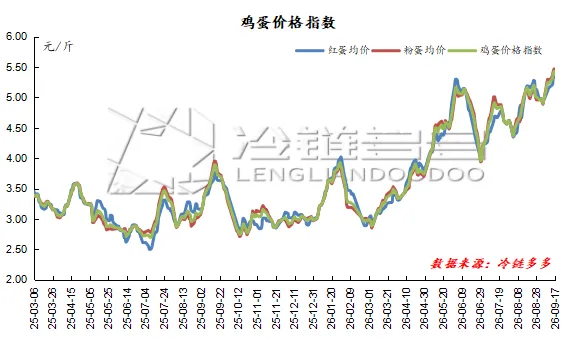
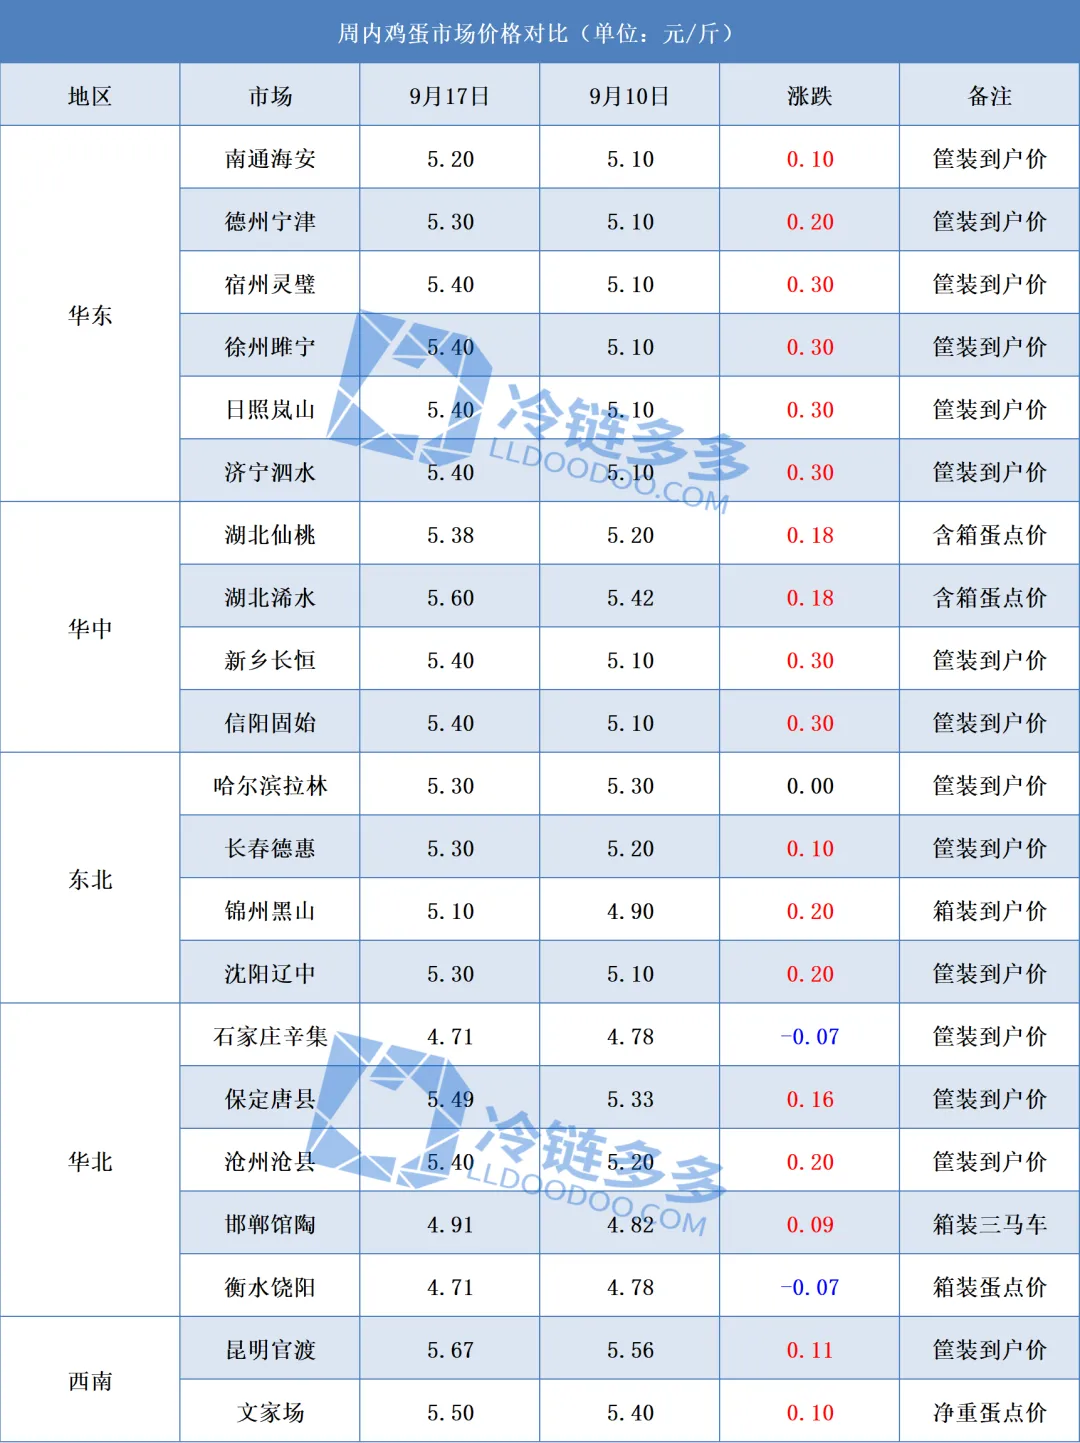
This week, domestic egg market quotes continued to show a narrow upward trend. As of Thursday this week, the average red egg price was 5.34 yuan/jin, up 0.19 yuan/jin from last week. The average pink egg price was 5.41 yuan/jin, up 0.12 yuan/jin from last week. The average prices of both red and pink eggs maintained their upward trend, with the price spread between the two narrowing to 0.07 yuan/jin. The egg market is currently in the final stage of Mid-Autumn Festival restocking, exhibiting a "strong reality, weak expectations" characteristic. Spot prices remain high supported by pre-holiday demand, but supply-side pressure is gradually accumulating, and the market generally holds a cautious attitude toward post-holiday trends.
Production Area Market
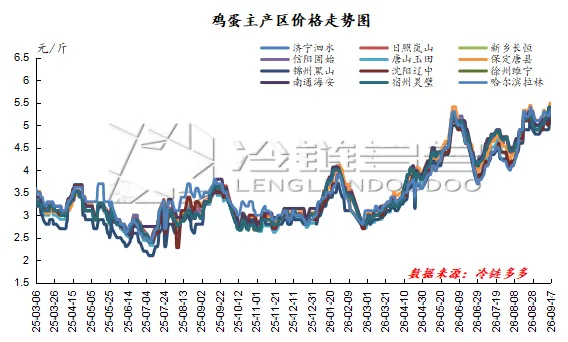
As of Thursday this week, the average price in major egg production areas was 5.35 yuan/jin, up 0.18 yuan/jin from the same day last week.
Sales Area Market
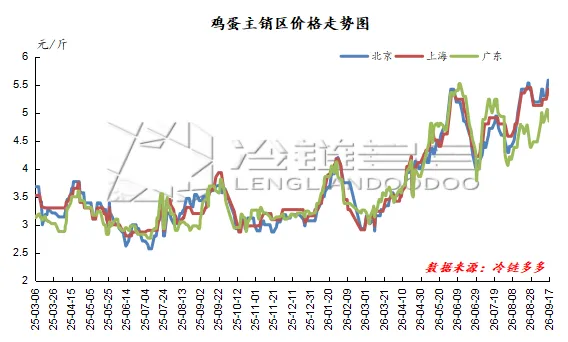
As of Thursday this week, the average price in major egg sales areas was 5.28 yuan/jin, up 0.09 yuan/jin from the same day last week.
1.2 Egg Market Price Trend Charts
II. In-Production Layer Inventory and Culling Analysis
2.1 Inventory Analysis
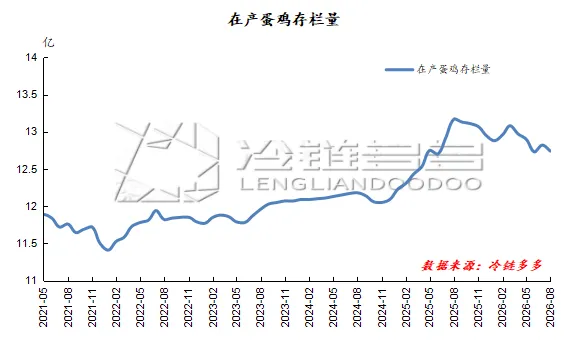
The proportion of old laying hens is currently high, with sufficient old hens available for culling. Chick placement volumes in April-May were at relatively high levels within the year, meaning that newly opened laying hens are about to see a wave of concentrated volume release, and the supply side will see significant improvement.
2.2 Culling Analysis
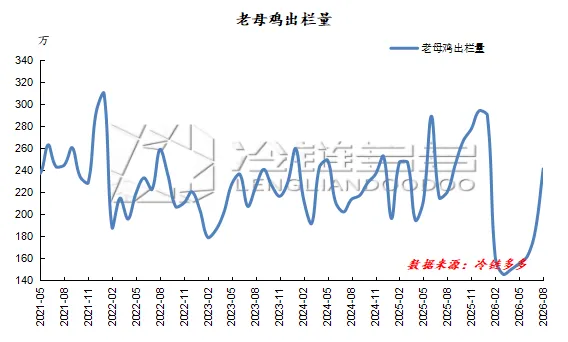
On the culling side, recent culling volumes have increased month-over-month. Most farmers remain bearish on the post-Mid-Autumn market, with most enterprises choosing to cull birds in a timely manner to avoid the risk of price declines. However, some operations, considering the substantial profits, continue to delay culling.
III. Egg Demand Analysis
Mid-Autumn Festival restocking has entered its final stage, with concentrated procurement by large mooncake manufacturers concluded. Terminal retail demand still has some support but limited sustainability. With egg prices at relatively high levels, traders' purchasing sentiment has turned cautious, mostly adopting a sell-as-you-buy, fast-in-fast-out approach. Willingness to actively stockpile is not strong.
IV. Market Forecast
From the supply side: High-temperature weather has ended, and egg production rates are gradually returning to normal. Newly opened production volumes continue to increase in September. However, most farmers remain bearish on the post-Mid-Autumn market, and culling sentiment on the farming side is rising, effectively offsetting the increase from newly opened production. Overall, farming operations are shipping birds in line with market conditions, and supply from production areas remains normal.
From the demand side: Mid-Autumn Festival restocking has entered its final stage, with concentrated procurement by food enterprises essentially concluded. Supermarket and terminal gift box orders are still being fulfilled, but marginal incremental growth has clearly weakened.
Overall: In the short term, spot prices are supported by low inventory and tail-end holiday demand, and egg prices may maintain high-level volatility, but the momentum for further gains is insufficient. As Mid-Autumn restocking concludes, demand will enter a seasonal decline period, while newly opened production continues to be released. The supply-demand relationship will shift from tight to loose, and egg prices face downward correction pressure. The expected adjustment magnitude is approximately 0.50 yuan/jin, with the average price in major production areas projected at 5.10-5.25 yuan/jin.