Egg Weekly: Prices Bottom Out and Rebound, Sustainability Remains Questionable(Oct 29)
Egg Weekly: Prices Bottom Out and Rebound, Sustainability Remains Questionable
Domestic Egg Market Analysis
1.1 Egg Market Price Analysis
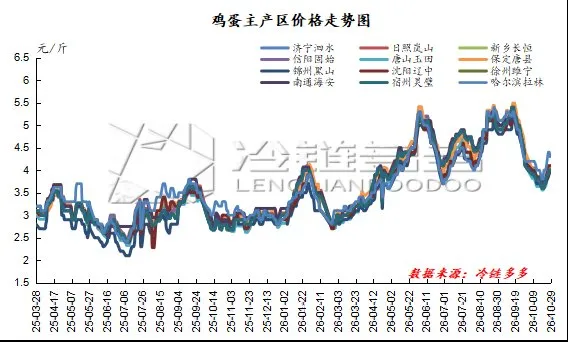
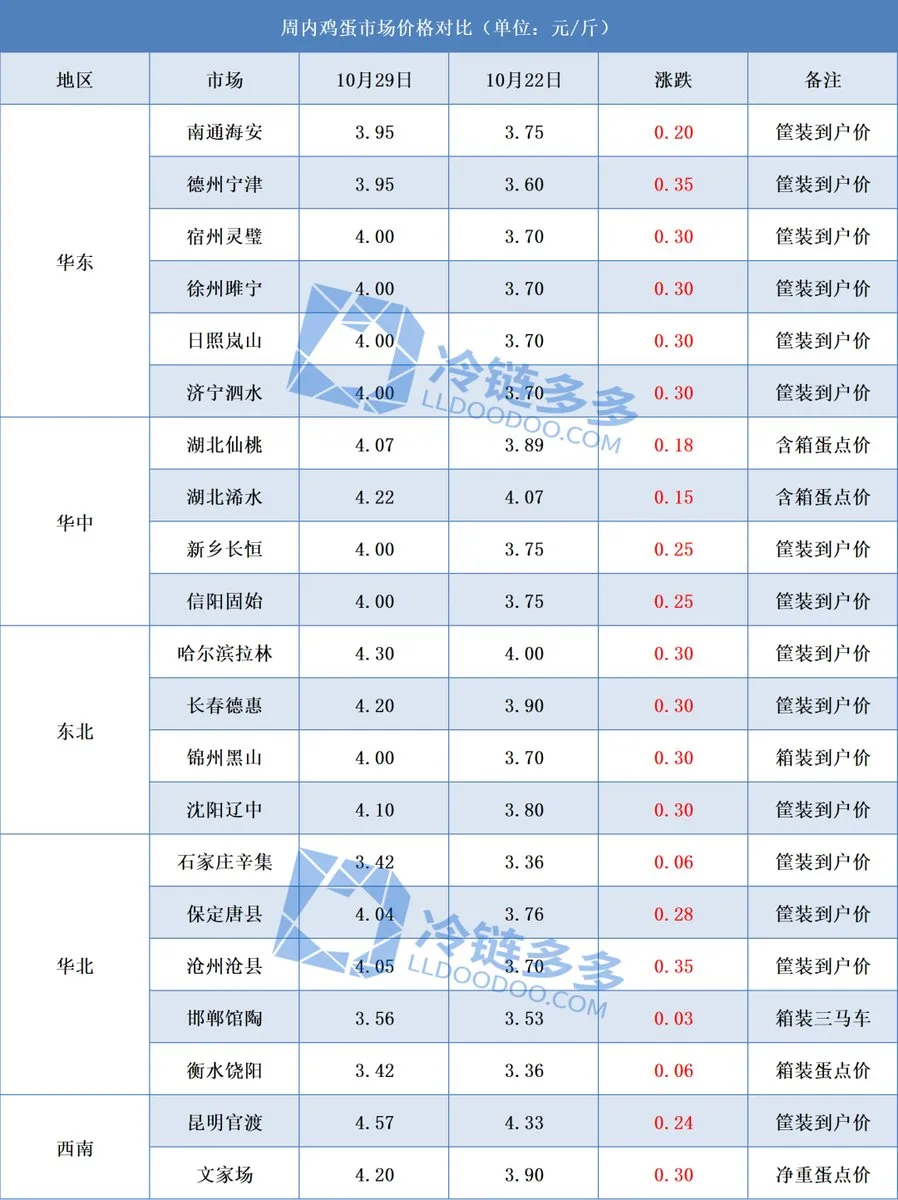
This week, domestic egg market quotes showed a slight upward trend. As of Thursday, the average red egg price was 4.08 yuan/jin, up 0.25 yuan/jin from last week. The average pink egg price was 4.04 yuan/jin, up 0.13 yuan/jin from last week. Both red and pink egg prices still maintained a declining trend, with the spread between the two at 0.08 yuan/jin. The loose supply pattern has not yet changed, and the demand side still lacks obvious positive catalysts, leaving overall supply and demand loose. However, as egg prices bottomed out at aphased level, bottom-fishing sentiment emerged in some production areas. Traders' willingness to purchase at low prices increased, shipment conditions improved slightly compared to earlier, and market sentiment warmed somewhat. This week the egg market wasrange-bound.
Production area market: As of Thursday, the average price in major egg production areas was 4.08 yuan/jin, up 0.24 yuan/jin from last Thursday.
Consumption area market: As of Thursday, the average price in major egg consumption areas was 3.99 yuan/jin, up 0.17 yuan/jin from last Thursday.
1.2 Egg Market Price Trend Charts
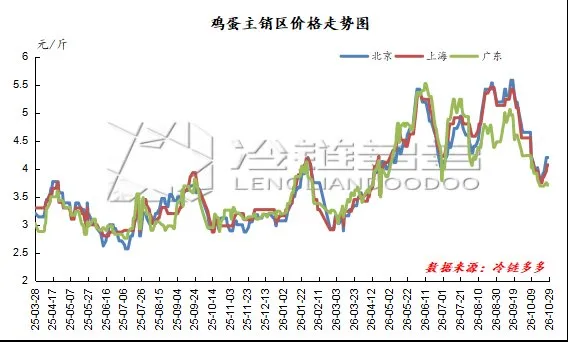
1.3 Weekly Domestic Egg Regional Market Price Comparison
Layer Flock Inventory Analysis
2.1 Inventory Analysis
In terms of total inventory, the farming side is currently in a marginal profit state with limited profit margins. Large farms mostly proceed steadily with planned restocking at a relatively stable pace. However, small and medium-scale farmers remain concerned about future market conditions, with strong wait-and-see sentiment and mediocre restocking willingness. Expansion enthusiasm is low. Overall, restocking sentiment on the farming side is clearly differentiated, and short-term restocking pace is likely to remain stable without significant volume increases.
Current layer farming profits are acceptable, and farming sentiment has diverged: some farming units plan to delay culling to extend the laying cycle and amortize costs, while others are selling opportunistically to lock in profits. Downstream poultry product consumption is sluggish, terminal shipments are slow, and slaughterhouses are cautious about purchasing at high prices with continued price-suppression intentions. Old hen prices remain stable with a wait-and-see approach.
Egg Demand Analysis
Demand remains weak. Food factories and supermarkets have no centralized restocking plans, procurement pace is steady, and downstream buyers primarily purchase on a just-in-time basis with weak proactive stockpiling willingness. The market lacks obvious demand catalysts. The trading sector mostly holds a wait-and-see attitude, restocking is limited to small just-in-time orders, and short-term trading is likely to remain flat. Price increases lack demand-side support.
Egg Market Outlook
On the supply side, as temperatures decline after autumn, laying rates are recovering from the summer lull, and daily egg output has increased month-on-month. Recently, with egg prices continuing to test upward, farmers' enthusiasm for culling hens has weakened somewhat, and some enterprises are adopting a wait-and-see approach with extended rearing.
On the demand side, after the National Day stockpiling ended, food factory, tourism catering, and household procurement demand have simultaneously retreated. The market has entered the traditional off-season, lacking holiday consumption catalysts, resulting inphased loose supply-demand conditions.
Overall, the egg market is currently in a loose pattern of "rising supply and weak demand." Egg prices have fallen significantly from pre-holiday highs, with the main production area average returning to the "4 yuan era." Short-term weakness and range-bound trading are expected to dominate. November may face the greatest downward pressure of the year, but the probability of prices falling below the cost line and triggeringconcentrated culling is limited. Bottom support remains, with expected adjustment of 0.30-0.50 yuan/jin, and the main production area average projected at 3.20-3.70 yuan/jin.
-
Egg Weekly: Prices Bottom Out and Rebound, Sustainability Remains Questionable(Oct 29)8646
-
China Becomes Norway's Second-Largest Seafood Market as Salmon Exports Reach 98,000 Tons in First 9 Months, Up 42%(Oct 29)6041
-
Uzbekistan Updates List of 241 Chinese Citrus Exporters Granted Market Access(Oct 29)6800
-
Eggs: Off-Season Lacks Catalysts, Market Remains Stable(Oct 28)7386
-
Ecuadorian White Shrimp Size Premium Distorted: Large Sizes Overpriced by $0.5/kg, Price Correction Expected After Fisheries Expo(Oct 28)9322